A practical guide to maintaining adequate health insurance while Condition 8501 applies.
The Visa Condition 8501 is short on paper but important in practice. It can affect the evidence you provide before grant, the insurance you arrange before travel and the cover you maintain throughout your stay. This guide explains what condition 8501 means, how OSHC and OVHC differ, what “adequate” cover generally includes and how to avoid an accidental gap.
Check your own visa grant: Condition 8501 applies to an individual visa. Confirm the conditions attached to your visa in the grant notification or VEVO before choosing or changing cover.
The legal effect of condition 8501 is that the visa holder must maintain adequate arrangements for health insurance while in Australia. It is a condition attached to an individual visa, not a general recommendation and not a rule that applies identically to every temporary visa holder.
Check your visa
Read the “Visa conditions” section of your visa grant notification or check your current visa details in VEVO.
Cover the required period
Choose the correct policy start date and maintain continuous cover while you are in Australia and condition 8501 applies.
Keep evidence
Retain your policy certificate, payment records, membership details and notices of any policy changes.
The purpose of 8501 visa condition health insurance is to reduce the risk that a temporary resident faces substantial medical costs without an adequate means of paying them. Many temporary residents are not eligible for Medicare and can be charged as private patients in either a public or private hospital.
Health examination and health insurance are different. A medical examination helps Home Affairs assess whether an applicant meets the health requirement. Insurance helps pay eligible healthcare costs during the insured period. Completing a visa medical does not satisfy condition 8501.
Which visas may have condition 8501?
Condition 8501 is associated with several temporary visa categories. For example, it commonly appears on Student visas and may apply to temporary work, graduate, guardian, sponsored parent and some visitor visas. The exact position depends on the subclass and the grant. A Visitor visa is not automatically subject to 8501 in every case, but Home Affairs may impose it in some circumstances.
Students and guardians
Student visa holders generally use Overseas Student Health Cover (OSHC). Student Guardian applicants may need evidence of adequate insurance for themselves and accompanying family members.
Temporary workers and graduates
Suitable Overseas Visitors Health Cover (OVHC) is a common solution. See VEM’s current guides to the Skills in Demand visa subclass 482 and related employer-sponsored pathways.
Secondary applicants should not be overlooked. If a partner or child has their own visa grant subject to condition 8501, make sure the policy covers them for the relevant period. Do not assume that the main applicant’s single policy automatically extends to every family member.
which visas may have condition 8501
What counts as adequate health insurance?
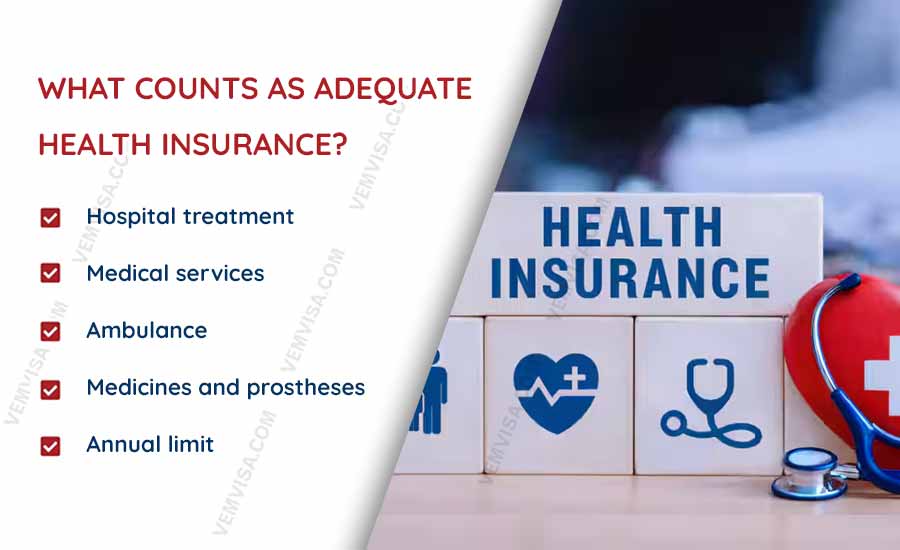
Home Affairs publishes a guide to benefit levels for temporary visa holders. It is not simply a requirement to possess any insurance certificate. When comparing health insurance for 8501 visa condition, confirm that the insurer considers the exact product suitable for your visa and that the cover is appropriate for everyone insured.
Hospital treatment
Admitted treatment in public hospitals at relevant state or territory rates for ineligible patients, including accommodation, theatre, intensive care and eligible emergency-department fees leading to admission.
Medical services
For admitted services with a Medicare Benefits Schedule item number, benefits of up to 100% of the MBS fee—or the amount charged, if lower.
Ambulance
Medically necessary ambulance transport for hospital admission, emergency treatment or eligible emergency inter-hospital transfers.
Medicines and prostheses
Specified benefits for eligible PBS medicines used during an admitted episode and listed surgically implanted prostheses.
Annual limit
A global annual benefit limit of at least AUD 1,000,000 per person.
A policy can still contain an excess, co-payment, waiting period, exclusion or benefit gap. Adequate insurance does not promise that every dollar of every treatment will be paid. Before treatment, ask the provider and insurer about likely out-of-pocket costs and obtain informed financial consent where possible.
Waiting periods and exclusions matter
Australian registered private health insurers may impose waiting periods. The government guide identifies maximum periods that can include:
12 months for pregnancy and birth-related treatment;
12 months for pre-existing conditions;
Two months for psychiatric treatment, rehabilitation or palliative care; and
Two months in other circumstances.
Some treatments may also be excluded, including elective cosmetic procedures, assisted reproductive treatment and treatment arranged before arrival.
Planning a pregnancy or managing an existing condition? Do not select cover by premium alone. Check the waiting period, clinical exclusions, hospital network, excess and likely start date before relying on a policy.
Compare OSHC, OVHC and travel insurance
OSHC
Overseas Student Health Cover is designed for international students and eligible dependants. It is the usual form of cover used to satisfy the student visa health-insurance requirement.
VEM’sStudent visa guide explains OSHC in the wider application checklist.
OVHC
Overseas Visitors Health Cover is commonly used by temporary workers, graduates, visitors and other non-student visa holders.
Product benefits vary significantly, and not every OVHC tier is marketed as meeting condition 8501.
Travel insurance
Travel policies are often designed for a trip rather than a long temporary stay. They may have lower limits, narrower healthcare benefits or exclusions that make them unsuitable.
Never assume a travel policy satisfies condition 8501 without written confirmation and a careful comparison with Home Affairs guidance.
The best type of 8501 visa condition insurance is therefore the one that fits the visa, required period and medical needs—not necessarily the cheapest plan or the product with the longest list of extras.
How to choose insurance for visa condition 8501
Step 1. Confirm that 8501 applies
Check your grant letter or VEVO. Record the visa validity, first-entry deadline and permitted stay so you can discuss accurate dates with the insurer.
Step 2. List every person who needs cover
Include each family member whose visa is subject to the condition. Check whether you need a single, couple, family or separate policy.
Step 3. Ask the insurer about your exact visa
Provide the subclass and state that condition 8501 is attached. Request written confirmation that the selected product is intended to meet the relevant visa requirement.
Step 4. Compare benefits, not just premiums
Review hospital and out-of-hospital benefits, ambulance, medicines, excesses, co-payments, waiting periods, exclusions and annual limits.
Step 5. Set the correct start date
Cover may need to begin before arrival or from the date required for the visa process. Avoid relying on a policy that starts after you enter Australia.
Step 6. Save the evidence
Keep the certificate, policy wording, receipts and written suitability confirmation. Make sure names, dates of birth and passport details are accurate.
Quick policy check: confirm condition 8501 + list every insured person + verify the exact visa subclass + compare benefits and exclusions + set the correct start date + save written evidence.
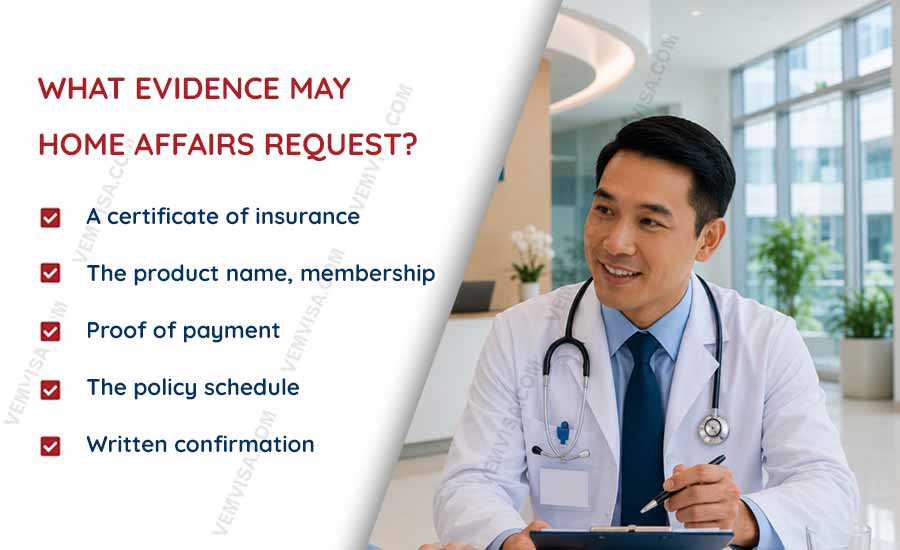
What evidence may Home Affairs request?
Home Affairs may ask for evidence of adequate arrangements before deciding an application. A current policy certificate from an Australian registered private health insurer is a common form of evidence, although private insurance from an overseas provider may also be acceptable in some circumstances.
A useful evidence pack may include:
A certificate of insurance showing the policyholder and every covered dependant;
The product name, membership or policy number and cover dates;
Proof of payment or active membership;
The policy schedule and relevant product disclosure information;
Written confirmation from the insurer that the selected product is suitable for the visa requirement; and
Medicare or RHCA evidence if you intend to rely on that arrangement and are eligible.
If Home Affairs sends a request for information, respond by the stated deadline and address the specific request. Applicants who need help interpreting a request or coordinating it with a wider application can review VEM’s Australian visa services.
Does Medicare satisfy condition 8501?
Medicare eligibility is not automatic for temporary visa holders. Australia has Reciprocal Health Care Agreements with certain countries, and eligible visitors may receive some medically necessary care under Medicare. However, eligibility, enrolment, duration and benefits depend on the agreement and the person’s circumstances.
Do not cancel private cover merely because your country has an RHCA. First confirm your own Medicare eligibility, enrol successfully, understand what the agreement covers and obtain advice about whether the arrangement satisfies the condition attached to your visa. RHCA benefits are not the same as comprehensive private insurance.
Switching insurers, late payments and gaps in cover
You can generally change insurers, but the transition must be planned so there is no uninsured period. Before cancelling an existing policy, obtain confirmation of the new policy’s start date, check how served waiting periods will be recognised and retain both certificates.
Common causes of an accidental gap include:
An expired bank card or failed direct debit;
Cancelling the old policy before the replacement starts;
Choosing an incorrect arrival or policy start date;
Forgetting to add a partner or dependant; and
Assuming an employer will arrange and maintain the cover.
An employer may assist, but the visa holder remains responsible for complying with the conditions attached to the visa.
If travel dates change, contact the insurer before departure. If you leave Australia permanently or receive a different visa, ask the insurer how the change affects cover and refunds. But do not terminate the policy until you have checked the conditions currently applying to you.
What happens if you breach visa condition 8501?
Failing to maintain adequate insurance can amount to a breach of a visa condition. Depending on the facts, it may expose the holder to visa cancellation consideration and can create difficulties in later immigration dealings. It can also leave the person personally responsible for significant hospital and medical bills.
If your policy has already lapsed, act promptly:
contact the insurer and confirm when the policy stopped;
ask about reinstatement and arrange appropriate cover;
keep all correspondence, certificates and payment records; and
seek professional advice about the immigration implications.
Do not backdate documents or provide information that is inaccurate.
Unsure how condition 8501 affects your visa? VEM‘s registered migration agent can help you identify the conditions attached to your visa and consider the immigration implications of a compliance issue.
Insurance-product advice and policy recommendations should be obtained from an appropriately authorised insurer or adviser.
FAQs
What does visa condition 8501 require?
It requires the visa holder to maintain adequate arrangements for health insurance while in Australia and while the condition applies.
Does completing a visa medical satisfy condition 8501?
No. A health examination is used to assess the visa health requirement; insurance helps pay eligible healthcare costs during the insured period.
Is travel insurance always enough for condition 8501?
No. Travel policies may have lower limits, narrower healthcare benefits or exclusions. Obtain written confirmation and compare the policy with Home Affairs guidance.
Can I switch insurers while condition 8501 applies?
Generally, yes, but plan the transition so there is no uninsured period and retain evidence from both policies.
Mr. Phong Cao is a licensed migration agent by MARA (MARN: 1577877). He is also a member of the Migration Institute of Australia (MIA: 12648), one of the most reputable organizations in the field of immigration in Australia. In addition, Mr. Phong Cao holds a QEAC certification in study abroad consulting (QEAC: K580) and Australian real estate investment (RA85931). With over 12 years of experience in Australian immigration, he provides comprehensive solutions for studying and settling in Australia.

 VN
 Người
đăng
 Ngày
cập nhật: